ServicesInsurance Claims
Insurance Claims in Lemoore, CA
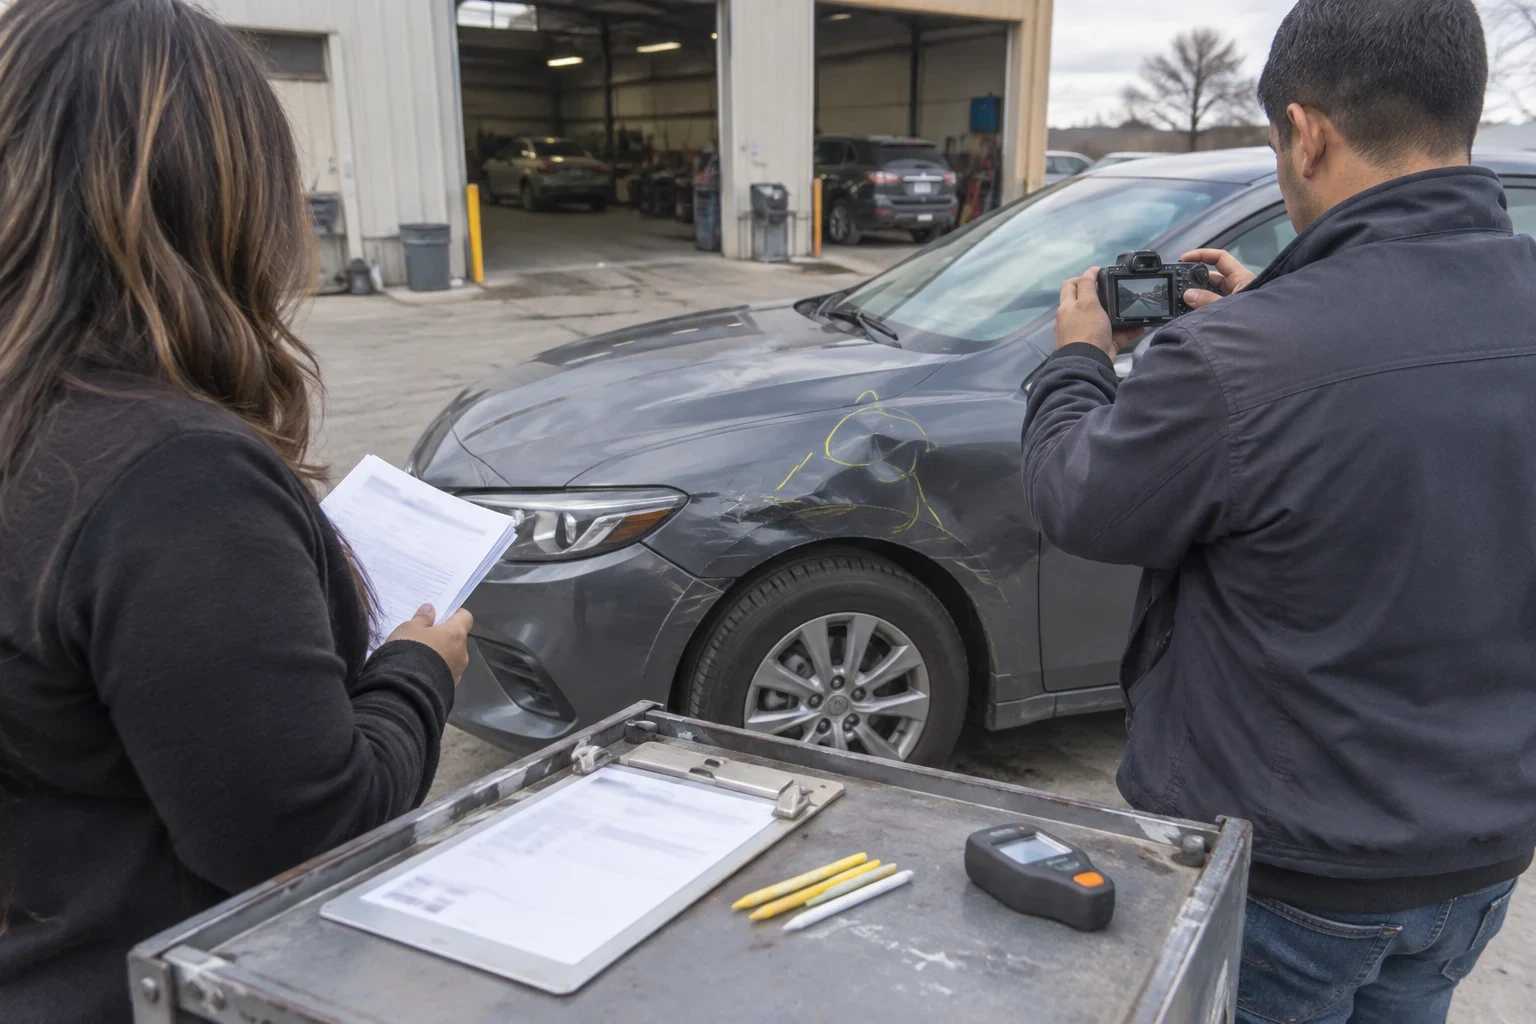
A wreck is stressful enough without guessing at the paperwork. We document the damage on your car, write a clear estimate and explain how the insurance process moves from first report to finished repair. We tell you what we know and what only your insurer can decide.
What we do when insurance is paying
Most collision work goes through insurance. The insurer wants proof of what was damaged. You want your car fixed right and a straight answer on what you will pay. Our job is the part in the middle: good photos, an honest estimate and plain talk about the next step.
We are not the adjuster. We do not set your coverage or decide your payout. What we can do is show the insurer exactly what is broken, explain why each part and labor line is on the estimate, and report back when we find more damage once panels come off.
Drivers from Lemoore, Hanford and Armona bring cars to us after all kinds of accidents, from a parking lot scrape to a hit that needs frame straightening. The steps are mostly the same. The amount of back and forth with the insurer is what changes.
What our insurance help includes
Photos of every damaged area
We take close and wide photos of the damage, the VIN and the mileage. You get copies. Insurers move faster when the pictures leave no questions.
A line-item written estimate
Each part, each labor operation and the paint time is listed on its own line. If something is on there, we can tell you why.
Working with the adjuster
We send the estimate and photos to your insurer and answer the adjuster's questions about the repair. Coverage questions still go to your insurer, and we will tell you when that is the case.
Supplements for hidden damage
Bent brackets, cracked mounts and sensor damage often hide behind a bumper cover. When we find it during teardown, we photograph it and send a supplement to the insurer before we do the added work.
Plain updates
We tell you when the estimate goes out, when the insurer approves it and when parts arrive. You should not have to chase us for news.
When it makes sense to call us
You just filed and do not know what is next
The insurer gave you a reference number and not much else. We can explain the usual order of things and what to have ready.
The insurer's estimate looks low
A quick photo estimate often misses damage you cannot see from the outside. We can look the car over and show you what else may be there.
The other driver was at fault
You may be going through someone else's policy. That changes who you deal with and sometimes who pays the deductible, so it helps to sort that out early.
Lights or sensors act up after a small hit
A minor bumper hit can knock parking sensors or a camera out of line. That damage belongs on the insurance estimate, but only if someone checks for it.
You were told to use a certain shop
Your insurer can suggest shops. In California, the choice of where your car gets repaired is yours.
How an insurance repair moves through our shop
- 1
Phone call
You tell us what happened, who your insurer is and whether you have a file number yet. We set a time for you to bring the car in.
- 2
Inspection and photos
We walk around the car with you, take photos and note anything you have noticed since the accident, like a pull in the steering or a new rattle.
- 3
Estimate to the insurer
We write the estimate and send it with the photos. Some insurers send an adjuster to see the car, and some approve from photos.
- 4
Teardown and supplements
Once approved, we take the damaged area apart. Anything new we find gets photographed and sent as a supplement, and we wait for approval before going further.
- 5
Repair and pickup
We finish the bodywork and paint, check the fit and gaps, and walk you through the final paperwork. You pay your deductible, if one applies, when you pick up your car.
What decides what you pay
On most insurance repairs, the insurer pays the approved repair cost and you pay your deductible. What lands on your bill depends on your policy and what the teardown shows. We will not guess at a number before we see the car.
- Your deductible
- If you go through your own collision coverage, your deductible is usually your share. If the other driver's insurer accepts fault, you may not owe one.
- Type of coverage
- Collision, comprehensive and liability coverage each pay for different things. Your policy sets what is covered, not the shop.
- Hidden damage
- Damage behind panels can raise the total once we open things up. Approved supplements are paid by the insurer, so finding it early protects you.
- Parts the policy allows
- Some policies pay for new factory parts, and others call for aftermarket or used parts. We show you what the estimate lists so you know what is going on your car.
- Extras you choose
- If you ask for work the insurer is not covering, like fixing an old door ding, we price that separately and in writing.
Questions about the insurance side
Something not covered here? (559) 524-4544
Do I have to take my car to the shop my insurer recommends?
No. In California you can choose where your car is repaired. The insurer may suggest shops it works with, but the decision is yours. Let your insurer know you want the car brought to us.
Will you talk to my insurance adjuster for me?
We talk with the adjuster about the repair itself: the damage, the parts and the labor. Questions about your coverage, fault or payout go between you and your insurer. We will tell you plainly when something is their call.
What happens if you find more damage after you start?
We stop, take photos and send a supplement to the insurer. Once they approve it, we keep going. You hear from us before any added work, so nothing shows up on your bill as a surprise.
Should I file a claim for small damage?
Sometimes it costs less to pay out of pocket than to go through insurance, especially with a high deductible. We can write you an estimate first so you can compare it with your deductible and decide. That choice is yours.
What should I bring when I drop off my car?
Bring the file number your insurer gave you, the insurer's name and the adjuster's contact info if you have it. Photos you took at the scene help too. If you have a police report or the other driver's information, bring that as well.
Can my car be declared a total loss?
Yes. If the repair cost gets close to the car's value, the insurer may total it. That decision is theirs, not ours. We will share what we found so you understand how they got there.
Already filed with your insurer
Give us a ring and tell us what happened. We will set a time to look at your car and walk you through what comes next.